MENA’s Open Finance opportunity in the age of AI
An article by Faisal Toukan, co-founder and CEO of Ziina
Every major technology platform tends to follow a similar evolution. It begins with the digitisation of individual products. Over time, those products become connected. Eventually, the competitive advantage shifts from what each product can do to how intelligently the system works as a whole.
Smartphones evolved this way. Hardware, software and services became one seamless experience.
Cloud computing evolved this way. Independent applications became interconnected systems capable of operating at a global scale.
Artificial intelligence is evolving the same way. The conversation has already moved beyond individual models to how multiple models, tools and workflows coordinate to solve increasingly complex tasks.
Finance has reached that same moment. Over the past two decades, financial innovation has produced extraordinary products. Digital banks transformed banking. Payment platforms accelerated commerce. Accounting software modernised finance teams. Investing became accessible from a smartphone. Each innovation solved an important problem.
Every financial decision, however, still depends on financial data scattered across multiple institutions and platforms. Businesses reconcile payments across systems. Consumers piece together balances, commitments and goals before making important financial decisions. The products have advanced rapidly, but the responsibility for connecting them has remained with the customer.
At Ziina, we see this fragmentation in the way businesses manage money every day. A business can receive payments through one system, hold funds in another, issue invoices somewhere else and manage its books on a separate platform. The business owner ends up becoming the integration layer. What looks like a collection of separate financial products to the industry feels like one financial life to the customer.
That fragmentation carries a real economic cost. Every hour spent reconciling information, transferring financial data between systems or making decisions with an incomplete financial picture reduces productivity. At a broader level, fragmented information can limit how efficiently capital flows through the economy.
Based on 2019 data, the International Finance Corporation (IFC) estimated the financing gap for micro, small and medium-sized enterprises (SMEs) across emerging and developing economies at $5.7 trillion. In the Middle East and North Africa (MENA), financing gaps were among the largest relative to GDP, averaging close to 30%.
A business may have healthy revenue, reliable customers and predictable cash flow, yet those signals can remain distributed across multiple systems. The institution making a financing decision sees only the information available to it. The business experiences the whole picture.
This is where connected financial systems change the equation.
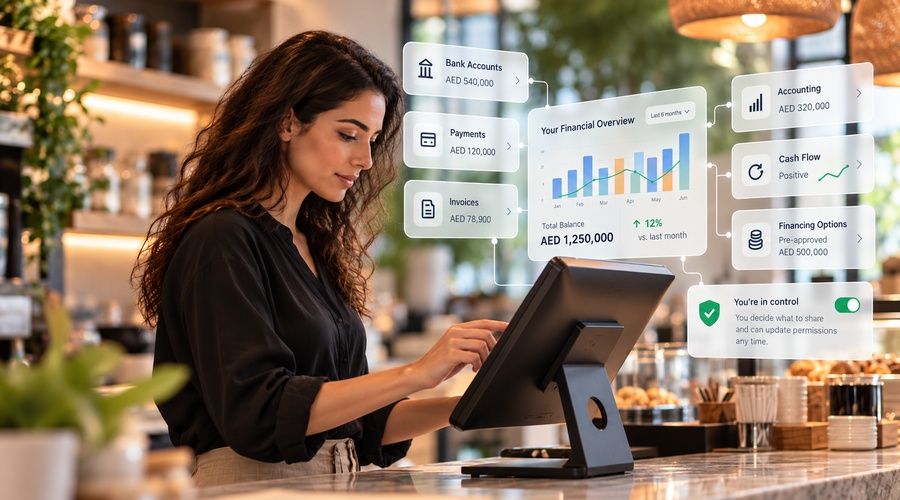
Imagine a business receiving a payment from a customer. The payment reaches the bank account. The accounting platform updates automatically. Cash flow projections refresh. Working capital is recalculated. Financing options adapt to the business’s latest financial position.
The payment itself is only the starting point. What matters is that every connected product works from the same context and responds in coordination.
The same principle applies to consumers. Financial guidance becomes far more useful when it reflects a more comprehensive financial picture rather than isolated snapshots. Income, savings, investments, recurring commitments and long-term goals all contribute to better decisions. Artificial intelligence makes those interactions conversational. Connected systems give them context, allowing financial products to work together instead of operating independently.
Open Finance provides the foundation for that coordination. By enabling customers to securely share financial data across institutions, it can give financial service providers a more connected view of a customer’s financial world. Banks, payment providers, lenders, accounting platforms and investment services can respond to the same financial context, subject to the customer’s consent and the services connected to the system.
Open Finance goes beyond Open Banking by extending connectivity beyond bank account data to a broader range of financial products and services.
The UAE is building this infrastructure at the ecosystem level. The Central Bank of the UAE’s Open Finance framework introduced common infrastructure for secure data sharing and transaction initiation, supported by an API Hub and Trust Framework. The significance is larger than any individual Open Finance product: It creates common rails through which financial institutions and fintechs can build connected experiences.
For markets across the Middle East and North Africa, this creates an unusual opportunity. Much of the region’s digital financial infrastructure is being developed at the same time that Open Finance and AI are becoming increasingly viable. That creates an opportunity to design systems around the needs of today’s consumers and businesses rather than yesterday’s infrastructure.
Brazil offers one of the clearest examples of where the industry is heading because its central bank approached Open Finance as an ecosystem capability rather than another financial product. Financial data shared with customer consent gives institutions a richer understanding of financial behaviour, creating the conditions for faster, more informed decisions.
The results are already visible. According to Banco Central do Brasil, between the beginning of Open Finance implementation in 2021 and June 30, 2025, R$31 billion in credit operations originated from the analysis of data shared through Open Finance. That included R$5.4 billion in new credit generated by fintechs for 6 million customers.
Brazil also shows what it takes to build Open Finance at the ecosystem level. It requires common standards for consent, authentication, security and data sharing. Those foundations create the trust required for customers to allow financial institutions and third parties to work with their data.
The UAE now has an opportunity to apply those lessons as it builds its own digital financial infrastructure at speed.
AI can reason across a financial context, while connected systems give it access to the systems and services required to act. This changes the role of AI in finance. Today, an AI system can explain a transaction, summarise spending or answer a question about a financial product. With access to connected financial infrastructure and the right permissions, it can begin to act on that understanding.
Consider a business owner facing a cash flow gap. An agent could see incoming payments, expenses, invoices and account balances, recognise that a shortfall is emerging, evaluate the available options and explain the trade-offs. With the right permissions, it could then take action and monitor the outcome.
The same principle applies to consumers. An agent could monitor recurring commitments across connected accounts, identify an upcoming liquidity requirement, move money between eligible accounts or initiate a payment according to rules established by the customer.
This is what financial agents make possible: systems that can understand financial context, make decisions within defined parameters and act on a customer’s behalf.
The harder question is how much authority we grant these systems.
An agent can analyse, recommend and prepare an action. The customer decides how much authority to delegate, within clearly defined permissions and controls. The more consequential the action, the more important transparency, authentication and human oversight become.
The industry will have to solve these questions as the technology develops. Who is liable when an agent makes a mistake? How should consent work when an agent acts continuously rather than during a single transaction? How much authority should a customer grant an agent?
These questions will determine how quickly financial agents move from an intriguing technology to something people trust with their money.
Every major technology platform eventually reaches a point where individual components become infrastructure for a larger system. Finance is entering that phase now, with value increasingly coming from connecting data, decisions and services into experiences that feel effortless for the customer.
For the Middle East and North Africa, the opportunity is significant. The region can build the connective infrastructure and intelligence layer together, with Open Finance creating trusted pathways between financial institutions and AI creating new ways to interact with them.
Open Finance gives us the connected financial system. AI gives that system intelligence. Financial agents give customers a way to turn that intelligence into action.
The result will be a fundamentally different way of building, delivering and experiencing financial services.

